Manufactured home loans: What buyers should know
Contributed by Tom McLean
Updated Sep 6, 2026
•9-minute read

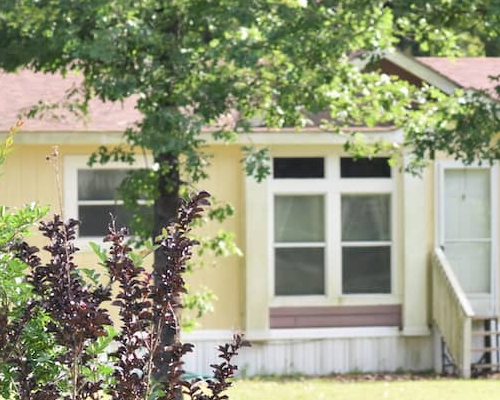
Manufactured home loans can turn an affordable, modern home into reality – if your property checks a few key boxes. Your financing options depend on when the home was built, how it’s anchored, and whether it’s titled as real estate. Learn more about eligibility, program types (FHA, VA, USDA, conventional, chattel), required documents, costs, and next steps so you can choose the right path with confidence.
Key takeaways:
- You can finance a manufactured home using conventional, FHA, VA, USDA, or chattel loans, depending on whether you own the land or rent a lot.
- Traditional mortgages require the home to be built after June 15, 1976, attached to a permanent foundation, and titled as real property.
- Gathering your HUD tag details, foundation engineering certificates, and property titles ahead of time prevents closing delays.
What are manufactured, mobile, and modular homes?
People often use the terms “mobile home,” “manufactured home,” and “modular home” interchangeably. However, each has a distinct meaning that directly affects your financing choices.
Mobile homes
A mobile home refers strictly to factory-built housing constructed before June 15, 1976, when the U.S. Department of Housing and Urban Development (HUD) established federal building and safety standards.
Because mobile homes were built before modern safety, structural, and energy efficiency codes were in effect, traditional mortgage lenders rarely finance them.
If you’re buying a pre-1976 mobile home, personal loans or chattel financing are typically required.
Manufactured homes
A manufactured home was built entirely in a factory after June 15, 1976, and conforms to HUD safety, structural, and energy-efficiency standards.
These homes are transported on a permanent steel chassis to an engineered permanent foundation. It’s legally converted to real estate and qualifies for standard mortgage financing like conventional, FHA, and VA loans.
Exploring the pros and cons of manufactured homes can help you decide if this housing path fits your long-term goals.
Modular homes
When evaluating modular vs. manufactured homes, the key distinction lies in building codes. Modular homes are constructed in a factory, then assembled on-site. They are built to meet the same local and state building codes that apply to traditionally built homes. Because they’re treated the same as site-built housing, obtaining standard financing for a modular home is straightforward.
See what you qualify for
Manufactured home loan requirements
Qualifying for standard manufactured home loans requires meeting specific eligibility criteria for both you and the property.
Property requirements
To qualify for traditional mortgage financing, the home must meet several foundational guidelines:
- HUD certification. The home must be built on or after June 15, 1976, and display an exterior red metal HUD Certification Label (HUD tag) on each section.
- Permanent foundation. The structure must be attached to a permanent foundation, such as a concrete slab or piers, with all towing hitches, wheels, and axles removed.
- Real property classification. In many states, the vehicle title must be surrendered or canceled at your state department of motor vehicles, so the home is legally classified and taxed as real property alongside the land.
- Structure and size. The unit must generally be a single-family dwelling that meets minimum square footage guidelines. Typically, it must be at 400 square feet.
Borrower requirements
Lenders also will evaluate your personal finances to ensure you’re set up for success:
- Credit score. Minimum credit score requirements vary by loan type. Government-backed options often accept scores starting at 580, while conventional loans usually require a score of 620 or higher.
- Debt-to-income ratio (DTI). Your DTI measures how much of your gross monthly income goes toward debt obligations. Aiming for a DTI below 43% gives you the strongest chance of approval.
- Down payment. Depending on the program, down payment options range from no down payment for eligible VA or rural buyers to 3%, 3.5%, or 5% for conventional and FHA programs.1
- Primary residence. Most government and conventional manufactured housing programs require you to occupy the home as your primary residence.
Documents you may need
Gathering these essential items early helps ensure a seamless loan approval process:
- HUD data plate and tag numbers. The HUD data plate is usually found inside a kitchen cabinet or electrical panel. You’ll also need photos of the exterior red HUD tags.
- Engineered foundation certificate. Stamped documentation from a licensed engineer verifying that the foundation meets HUD guidelines.
- Real property titling documents. Documentation confirming the vehicle title has been retired, and the home’s been converted to real property.
- Specialized appraisal. A property appraisal conducted by a certified appraiser experienced in manufactured housing guidelines.
- Standard financial documentation. Recent pay stubs, W-2 forms, income tax returns, and bank statements.
Take the first step toward the right mortgage
Apply online for expert recommendations with real interest rates and payments
Manufactured home loan options
Finding the right loan comes down to how your property is set up and whether you own the land. Here are the primary financing avenues available.
Conventional loans
A conventional loan is a mortgage that’s not backed by any government agency. It’s the most common loan type in the United States for buying a permanent home and can also be used to buy a manufactured home.
Many conventional loans are conforming loans, which means they meet specific requirements, including a conforming loan limit, that allow lenders to sell them to Fannie Mae or Freddie Mac. This reduces the lender’s risk when making conforming loans and gives them cash to make additional loans.
Both you and the property must meet specific requirements for a conforming conventional loan. Lenders will look at your personal finances, including these factors:
- Your credit. Fannie and Freddie recently dropped their requirement for a specific credit score, but lenders still review your credit history and establish their own minimums.
- DTI: Keeping your DTI below 43% is ideal for qualifying.
- Down payment or equity amount: Your down payment should typically be at least 5% if you want to purchase a manufactured home or do a rate-and-term refinance. For cash-out refinances, you’ll need at least 35% equity left in the home, the property cannot be a single-wide home, and the maximum loan term is 20 years.
Rocket Mortgage offers conforming loans for single-unit manufactured homes, requiring a down payment of 5% and a maximum DTI of 50%. Your credit will be reviewed and considered, but there’s no strict minimum credit score. Check today’s Rocket Mortgage rates.
Fannie Mae offers the MH Advantage program, which requires a down payment of at least 3%. Freddie Mac offers the CHOICEHome® Program for multisectional manufactured homes with at least 1,000 square feet of space, which also requires a minimum 3% down payment.
When buying a manufactured home with a conventional loan, you can access a standard competitive mortgage interest rate with terms up to 30 years. If your down payment is less than 20%, you’ll pay for private mortgage insurance (PMI) until you reach 20% home equity.
FHA loans
Backed by the Federal Housing Administration, FHA loans for manufactured homes offer low down payments, flexible credit terms, and low closing costs. You’ll need to satisfy standard FHA eligibility guidelines and occupy the property as your primary residence.
FHA Title I vs. FHA Title II loans
FHA offers two distinct loan programs for manufactured housing:
- FHA Title I Loans. Specifically designed to finance or refinance the home, the land lot, or both. Title I loans allow you to purchase a home even if it sits on a leased lot in a community.
- FHA Title II Loans. Insures the manufactured home and the land together under a single mortgage. Title II requires a minimum 3.5% down payment and credit scores starting around 580.
VA loans
VA loans are available only to eligible active-duty military personnel, veterans, and their surviving spouses.2
They offer $0 down payment options, competitive interest rates, and no ongoing PMI requirements. You may need to pay a VA funding fee at closing.
Rocket Mortgage requires a minimum credit score of 620 for VA loans and 640 for VA jumbo loans.
USDA loans
USDA manufactured home loans are targeted toward low-to-moderate-income buyers in qualified rural and suburban areas. USDA loans require no down payment and feature competitive interest rates. To qualify, the home must be a new manufactured unit attached to an approved permanent foundation and titled as real estate.
Rocket Mortgage currently doesn’t offer USDA loans.
Chattel loans
Chattel mortgages are specialized loans for personal property that isn’t tied to land ownership. If you plan on renting a plot for your manufactured home, a chattel loan is frequently used. While interest rates are generally higher than for traditional mortgages, and loan terms usually max out at 20 years, chattel loans offer a viable option when real property financing isn’t available.
Rocket Mortgage currently doesn’t offer chattel mortgages.
Personal loans
Unsecured personal loans for manufactured homes can work when financing smaller amounts or older homes that don’t qualify for traditional mortgages. Personal loans don’t require land collateral or complex property inspections, allowing them to close quickly. However, because they lack collateral protection for the lender, interest rates are higher, and repayment terms are shorter.
How to choose the right manufactured home loan
To narrow your options, match your financing choice to your land ownership situation.
If you are buying the home and land together
If you plan on exploring how to buy a manufactured home and land, standard real estate mortgages offer lower interest rates and longer repayment terms. Look into conventional, FHA Title II, VA, or USDA options through specialized banks that finance mobile homes with land.
If you are buying only the home
If you already own land outright and need to buy and install the home itself, consider an FHA Title I loan or chattel loan.
If the home sits on leased land
When financing a manufactured home on leased land, such as a lot inside a manufactured housing community, traditional real estate mortgages don’t always apply. In these cases, consider FHA Title I or chattel loans.
Apply for a conventional mortgage now
Rocket Mortgage® lets you do it all online and provides expert recommendations
How to apply for a manufactured home loan
Ready to begin? Following these steps will help you move smoothly from browsing to closing:
- Compare manufactured home lenders
- Gather your home and title documents
- Estimate your payment and total costs
Manufactured home costs and benefits
It’s important to understand the costs and benefits of buying a manufactured home.
Affordability
Manufactured homes provide exceptional value. According to industry data, the average cost of a new single-wide manufactured home was $90,700 in March 2026. By comparison, the U.S. median sales price was $409,000 as of June 2026, making the overall cost of a new manufactured home a compelling option for budget-conscious buyers.
Safety and durability
Since HUD standards were established in 1976, manufactured homes have been built to meet federal safety, fire resistance, structural, and energy efficiency codes. Homes built since the 1990s come with advanced wind safety engineering, making modern manufactured housing as safe and resilient as stick-built structures.
Build time and customization
Because manufactured homes are built inside climate-controlled factories, construction moves quickly without weather delays. Buyers can choose from various layout configurations, modern kitchen updates, and custom finishes to personalize their space.
Delivery costs and other expenses
While base costs are lower, remember to budget for setup and delivery fees. Transporting a manufactured home from the factory to your site will add thousands of dollars to the total cost, so buyers should budget accordingly.
What sellers need to know
If you’re selling a manufactured home, you’ll need answers to the following questions before putting it on the market.
Is it real property?
For buyers to finance their purchase with a mortgage, the home must be real property. This means that it’s permanently affixed to the foundation and the land and home are taxed together. You should be able to see this on the title.
Is there an outstanding vehicle title?
It’s often the case that manufactured homes are initially considered a vehicle for title purposes. Not every state requires you to surrender the vehicle title to convert the home to real property. However, when you go to sell, working through this can require additional time and fees.
Do you have the data plate and HUD certificates?
If either of these is missing or damaged, the lender and appraiser will need letters from the Institute for Building Technology Safety. These serve as evidence that the home passed the initial HUD inspection. If you need to order the letters, there’s a cost, and it can take up to 2 weeks to get them. Having the information available in advance can avoid delays.
Has there been an addition to the home?
If there has, you’ll need evidence of a structural inspection valid in your jurisdiction. It doesn’t matter whether the inspection is done at the time of the addition or at some point thereafter, but this is necessary to confirm the structural integrity of the home.
FAQ
Here are answers to common questions about manufactured home loans.
Is it difficult to get a mortgage on a manufactured home?
Getting a mortgage on a manufactured home shouldn’t be a problem as long as the home meets fundamental eligibility guidelines. If the home was built after June 15, 1976, is set on a permanent foundation, and is legally titled as real estate alongside the land, qualifying for a mortgage is very similar to buying a standard stick-built home.
What is the best lender for manufactured homes?
This depends on your financial profile and property type. Look for experienced lenders offering flexible government-backed loans, standard conventional options, and dedicated customer support.
Can you get manufactured home loans with bad credit?
Yes, if you’re searching for manufactured home loans with bad credit, government-backed options like FHA loans allow credit scores as low as 580 with a 3.5% down payment from Rocket Mortgage.3
Are manufactured home loan rates different from mortgage rates?
If your manufactured home is titled as real estate and financed through a conventional, FHA, or VA mortgage, manufactured home loan rates are very similar to standard mortgage rates.
The bottom line on manufactured home loans
Manufactured homes offer a combination of quality, modern features, and outstanding affordability. By exploring your financing options, whether through conventional, FHA, VA, USDA, or chattel loans, you can find a path to homeownership that aligns perfectly with your goals.
If you’re ready to take the next step on your home buying journey, you can explore your financing options today with Rocket Mortgage.
1 The 3% down payment option is only available on certain conventional loan products and is not available in all states. Additional terms and conditions may apply.
Rocket Mortgage is a VA-approved lender, not endorsed or sponsored by the Dept. of Veterans Affairs or any government agency.
3 To qualify for this offer, you must meet all standard FHA eligibility requirements. In addition, your total mortgage payment, including taxes and insurance, cannot exceed 38% of your income, your debt-to-income (DTI) ratio cannot exceed 45%, and you must have 12 months of verifiable housing history immediately prior to your application, no late payments 30 days or greater in the last 12-months, and no derogatory marks on your credit report. Not available on jumbo loans. Asset statements may be needed, no more than 1 day of non-sufficient fund fees are allowed in the most recent 2 months prior to application. Additional restrictions/conditions may apply.
Chibuzo Ezeokeke
Chibuzo has spent more than three years on Redfin’s Content Marketing team, specializing in homeownership tips and the move-in process. He creates practical, easy-to-follow resources that help new homeowners navigate everything from settling into their first property to building long-term equity. When he’s not writing about homeownership, Chibuzo enjoys running, playing basketball, and envisioning his dream Mediterranean-style home with a spacious kitchen and plenty of natural light.
Related resources
10-minute read
Manufactured homes: Defined and explained
Manufactured housing refers to a specific type of prefabricated home and can offer an affordable path to homeownership. Learn the pros and cons and more.
Read more
8-minute read
How to buy a manufactured home and land
Curious about how to buy a manufactured home and land together? Here’s what you need to know about home and land packages and manufactured home loan optio...
Read more
13-minute read
How to finance manufactured and mobile home loans
Mobile home loans can work differently than traditional mortgages. Read on to see your financing options, requirements, and how to qualify.
Read more